Personal income tax (IRPF) is levied on the income of tax residents in Andorra. The standard rate is 10%, and the first 24,000 euros are exempt.
Who is a tax resident
Anyone who spends more than 183 days of the calendar year in Andorra, or whose main centre of activities or economic interests is there.
How it is calculated
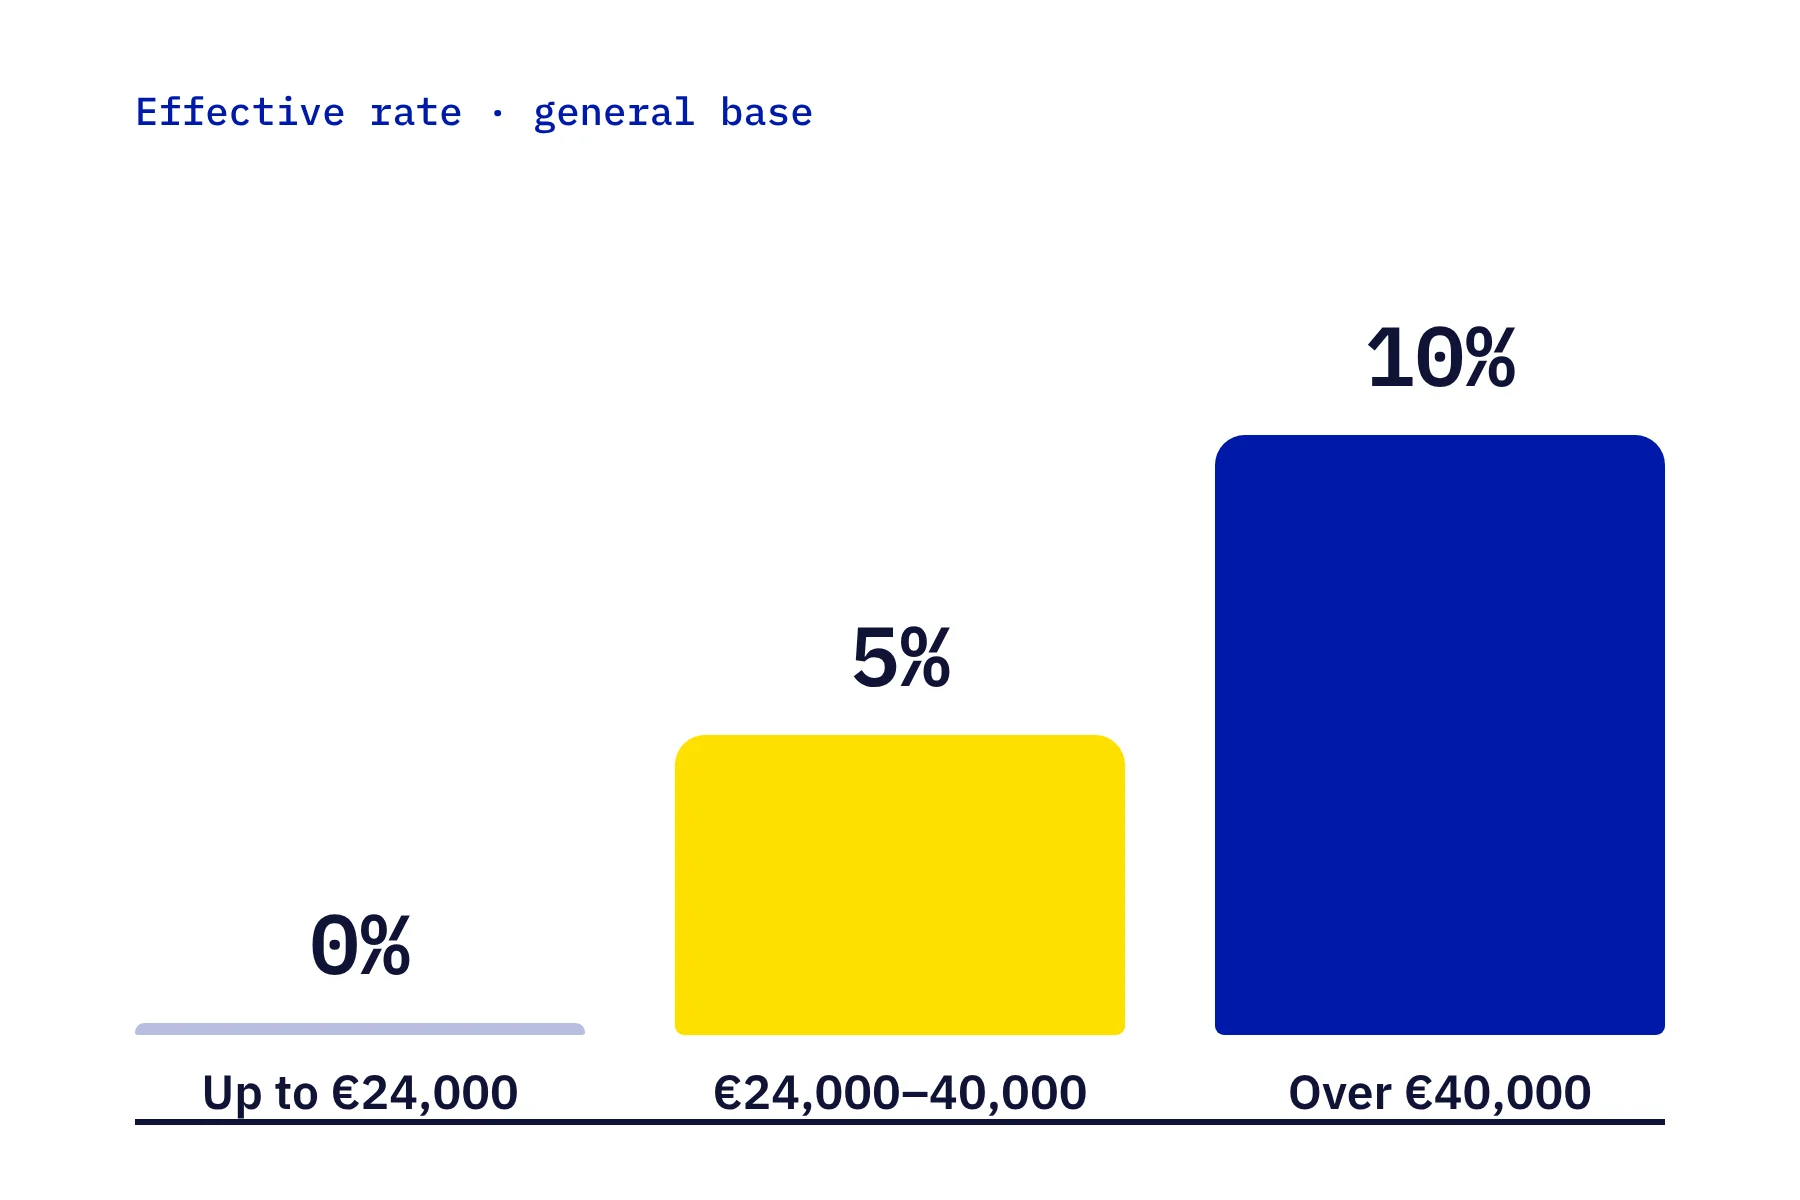
- Up to 24,000 euros: exempt personal allowance (30,000 with a recognised disability; 40,000 if your spouse has no general-base income).
- From 24,000 to 40,000 euros: 10% rate with a 50% reduction, capped at 800 euros: in practice, 5%.
- Above 40,000 euros: 10%.
When to file
From 1 April to 30 September of the following year. Anyone whose only income is employment income with tax withheld, below 24,000 euros gross, does not have to file.
General information based on the Government of Andorra's IRPF Guide (2025 income); this is not tax advice. For a specific case, ask your accountant.
From theory to tool. NominaAND calculates payroll with Andorran IRPF and CASS for accountancy firms and businesses. Find out more.